
Mutual Divorce and Bank Accounts, Investments and…
Mutual divorce and bank accounts, investments and financial assets in Pune: understand joint accounts, fixed…
EXCELLENT Based on 66 reviews
 Posted on Google

 Nabeel AkhtarFacing a criminal case can be stressful, but Advocate Nikhil Rathod made the entire process manageable. His strategic approach and strong representation gave me great relief.Posted on Google
 Srinath KarliAn experienced and sharp lawyer. Truly fast and great precise advocacy services offered. Highly recommended! Thankyou.Posted on Google
 SHIVA GAIKWAD
Trustindex verifies that the original source of the review is Google.
Good experience 👍👍👍👍Posted on Google Mangesh LawandeBest advocate for getting justice in Pune he is a very kind by nature 😊✨💫
That. Tax considerations can become important when a mutual divorce settlement involves alimony, a house or flat, jewellery, investments, shares, bank deposits or other valuable assets. A matrimonial settlement records the rights and obligations agreed between the spouses, but the tax consequences of implementing those terms may arise separately under the applicable income-tax and other laws.
That. The tax position also requires particular care in 2026 because the Income-tax Act, 2025 came into force from 1 April 2026 for the new tax years. The Income Tax Department has clarified that tax years beginning before 1 April 2026 continue to be governed by the Income-tax Act, 1961, while Tax Year 2026–27 onwards is governed by the new Act. Therefore, the relevant tax year and the nature of the transaction should be identified before drawing a conclusion about tax liability.
That. There is no simple universal rule that every amount described as “alimony” is automatically taxable or automatically exempt. Indian tax decisions have considered the legal character and circumstances of the payment, including whether it is a lump-sum amount settling matrimonial rights or recurring maintenance.
That. In Princess Maheshwari Devi of Pratapgarh v. Commissioner of Income-tax, the Bombay High Court considered monthly alimony and a lump-sum payment separately. The Court treated the lump-sum payment in the facts of that case as a capital receipt, while the periodic maintenance was treated differently for tax purposes. Later decisions, including Meenakshi Khanna v. Department of Income Tax, have considered the circumstances in which a lump-sum matrimonial settlement may constitute a capital receipt.
That. These authorities should not be converted into a blanket statement that every modern divorce settlement is tax-free. The wording of the settlement, nature of the payment, applicable tax year and surrounding facts should be examined before filing the relevant return.
That. A settlement may provide for a single payment, instalments, monthly maintenance, a combination of alimony and property transfer, or a payment specifically described as full and final settlement. The tax analysis can differ depending upon the legal character of the receipt.
That. The Bombay High Court’s decision in Princess Maheshwari Devi remains relevant as a judicial authority on the distinction between a capital receipt and recurring maintenance, but it arose under the older statutory framework. The new Income-tax Act, 2025 should therefore be considered for transactions falling within its applicable period.
That. A settlement should accurately describe the commercial and matrimonial substance of each payment. If a payment is towards permanent alimony, it should not be inaccurately described as a property sale consideration merely to obtain a perceived tax advantage.
That. Similarly, if a payment represents the value of identified jewellery or stridhan, the settlement should say so. If an amount relates to child education or child maintenance, that should be separately identified. Clear drafting helps distinguish different obligations and creates a documentary record of what the parties actually agreed.
That. Transfer of an immovable property as part of a matrimonial settlement requires separate examination. The parties should identify the nature of the transfer, the ownership before transfer, the consideration or settlement obligation, the relevant dates, the stamp-duty position and the applicable income-tax provisions.
That. The Income Tax Department explains that, under the earlier Income-tax Act, the concept of “transfer” for capital-gains purposes was broad and could include sale, exchange, relinquishment, extinguishment of rights and specified transactions concerning immovable property. Similar analysis must be undertaken under the applicable law for the relevant tax year.
That. A divorce settlement should therefore not simply state that a flat is being “given” to one spouse without examining the underlying ownership and legal instrument through which the transfer is to be implemented.
That. The legal effect of a matrimonial decree and settlement must be distinguished from the formal requirements for changing title or completing an immovable-property transaction. Depending upon the circumstances, a separate conveyance, release, transfer, partition or other document may be required, together with registration and stamp-duty compliance.
That. The parties should obtain appropriate property and tax advice before finalizing a clause concerning transfer of a house, flat, land or other immovable property. The settlement should also state who will bear stamp duty, registration charges and transaction-related expenses where applicable.
That. If the matrimonial settlement requires a property to be sold and the sale proceeds divided, the transaction should be analyzed as a property sale rather than simply as an alimony payment. Capital-gains consequences can arise based on the nature and holding period of the asset and the applicable tax provisions.
That. The Income Tax Department’s current guidance confirms that capital gains arise from transfers of capital assets and explains the breadth of the statutory concept of transfer. The exact computation depends upon the asset, acquisition history, improvements, consideration and the law applicable to the relevant tax year.
That. A settlement may provide for transfer or retention of shares, mutual fund units, bonds or other investments. If an investment is sold or redeemed to fund an alimony payment, the sale or redemption may have separate tax consequences for the person disposing of the asset.
That. The parties should therefore distinguish between the matrimonial settlement amount and the tax consequences of liquidating an asset to generate that amount. A spouse who sells shares to raise ₹20 lakh, for example, should not assume that the entire transaction is tax-neutral merely because the proceeds are subsequently paid as matrimonial settlement.
That. Where fixed deposits, savings balances or other interest-bearing accounts are divided or transferred, the principal amount and interest component should be distinguished. Interest earned before or after settlement may have separate tax treatment according to the applicable provisions.
That. Bank statements and interest certificates should be retained, particularly where the settlement involves substantial financial assets. The settlement should also identify whether an amount represents accumulated savings, interest, alimony or another agreed payment.
That. Income-tax returns, Form 26AS or its applicable successor records, annual information statements, salary records, bank statements, investment statements and loan documents can help establish the financial position of the parties.
That. The Supreme Court has repeatedly considered income, assets and liabilities when determining matrimonial financial arrangements. In 2025, the Court considered income-tax returns and bank statements while examining permanent alimony, and directed disclosure of relevant financial information. The precise disclosure required depends upon the proceeding and the court’s directions.
That. A settlement may contain separate provisions for a child’s education, medical expenses, maintenance and welfare. These amounts should not automatically be described as alimony payable to the spouse. The settlement should identify the beneficiary and purpose of the payment clearly.
That. Recent Supreme Court matrimonial settlements demonstrate that courts may separately record amounts for a spouse’s alimony and amounts earmarked for a child’s education or welfare. In one Supreme Court settlement, ₹80 lakh was recorded towards permanent alimony and an additional ₹10 lakh towards stridhan, with the latter directed into a fixed deposit in the name of the minor son. The arrangement was specific to that case and is not a general tax rule.
That. Return of jewellery or stridhan should be distinguished from a sale of jewellery. If identified jewellery belonging to the wife is simply returned to her, the transaction should be documented as return of her property rather than inaccurately characterized as a fresh purchase.
That. If jewellery is sold and a monetary amount is paid instead, the tax consequences of the sale and the nature of the resulting settlement should be examined separately. Bills, valuation reports and the settlement inventory should be retained.
That. The recipient should not simply omit a substantial divorce-related receipt from tax records without examining its legal and tax character. Even where a judicial authority supports capital treatment in particular circumstances, the recipient should maintain the decree, settlement agreement, payment proof and relevant tax analysis.
That. A clear explanatory trail can be particularly useful where a significant bank credit appears in the recipient’s account. The recipient should be able to demonstrate whether the amount represents alimony, return of capital, transfer of an asset, child-related payment or another category.
That. A payer should not assume that a matrimonial alimony payment is automatically deductible from taxable income merely because it is ordered by a court or recorded in a settlement. Deductibility depends upon the applicable tax provisions and the nature of the payment.
That. Matrimonial settlements should therefore not be drafted on the assumption that the payer will receive a deduction unless the applicable tax law specifically supports that treatment.
That. A full-and-final settlement clause is primarily a matrimonial arrangement. It does not itself determine tax liability. The tax treatment follows the applicable tax law and the legal substance of the transaction.
That. For example, describing ₹50 lakh as “full and final settlement” does not by itself answer whether it is alimony, consideration for an asset, repayment of a liability, return of property or another receipt. The supporting settlement terms and underlying transaction must be examined.
That. The Income Tax Department has confirmed that the Income-tax Act, 1961 was repealed with effect from 1 April 2026, while provisions of the old Act continue to govern tax years beginning before that date and related proceedings. For Tax Year 2026–27 onwards, the Income-tax Act, 2025 applies.
That. This means that a legal article or tax opinion relying entirely on provisions and terminology of the 1961 Act may not be sufficient for a settlement implemented in the new tax regime. The relevant tax year, transaction date and transitional provisions should be checked.
That. Common mistakes include assuming that every alimony receipt is automatically tax-free, treating a property transfer as equivalent to cash alimony, ignoring capital gains on the sale of an asset, failing to distinguish child-related payments from spousal payments, overlooking stamp-duty and registration issues, and failing to preserve documents explaining a substantial bank credit.
That. Another mistake is relying on an old tax-year decision without checking the law applicable to the current transaction. The transition from the Income-tax Act, 1961 to the Income-tax Act, 2025 makes this particularly important for settlements implemented after 1 April 2026.
That. Supreme Court matrimonial orders in 2026 continue to record detailed settlements involving permanent alimony, stridhan, instalment payments and child-related financial arrangements. For example, a May 2026 Supreme Court order recorded ₹80 lakh towards permanent alimony and ₹10 lakh towards stridhan in a case-specific settlement. Another Supreme Court matter in February 2026 recorded permanent alimony of ₹35 lakh payable in instalments.
That. These orders illustrate the variety of financial arrangements that may be incorporated into matrimonial settlements. They do not prescribe a standard amount of alimony or a universal tax treatment. Tax consequences must be considered separately under the law applicable to the particular transaction.
That. Tax planning should form part of the financial review before a substantial mutual divorce settlement is finalized in Pune. Alimony, property, investments, jewellery, bank deposits and child-related payments should be identified separately, and the settlement should accurately describe the substance of each transaction.
That. In 2026, particular attention should be paid to the transition from the Income-tax Act, 1961 to the Income-tax Act, 2025. Older judicial authorities remain relevant to the periods and legal questions to which they apply, but the applicable tax year and current statutory framework must be checked before implementation.
That. Taxability cannot be determined solely from the label “alimony.” Judicial decisions have treated certain lump-sum matrimonial receipts as capital receipts in particular circumstances, but the applicable tax year, transaction structure and facts must be examined.
That. Indian judicial decisions have distinguished periodic maintenance from certain lump-sum matrimonial receipts. The exact tax position should be checked under the law applicable to the relevant tax year.
That. For Tax Year 2026–27 onwards, the Income-tax Act, 2025 applies. Earlier tax years continue under the Income-tax Act, 1961 subject to the transitional provisions.
That. It should not be assumed to be automatically tax-free. The nature of the transfer, ownership, consideration, applicable capital-gains provisions and the legal instrument used should be examined.
That. Parties may agree to transfer an asset as part of a matrimonial settlement, but the property, stamp-duty, registration and tax consequences should be separately examined.
That. A sale of a capital asset can have capital-gains consequences. The computation depends on the asset, acquisition history, consideration and applicable tax provisions.
That. Return of property belonging to the woman should be distinguished from income or a fresh purchase. The documentation should accurately record the nature of the transaction.
That. Parties may agree upon the treatment of shares, but the transfer or sale can have separate securities, regulatory and tax implications.
That. Yes. Child maintenance, education and medical expenses should preferably be identified separately from the spouses’ own alimony or financial claims.
That. No. The settlement is evidence of the parties’ agreement, but tax liability is determined under the applicable tax law based on the substance of the transaction.
That. Yes. The settlement, decree, bank statements, payment proofs, property documents and investment records should be preserved according to the applicable record-keeping requirements and practical needs.
That. No automatic deduction should be assumed. Deductibility depends upon the applicable tax provisions and the nature of the payment.
That. Parties can record responsibility for taxes, stamp duty, registration charges and transaction costs, but a private clause cannot override statutory tax liability.
That. Where the settlement involves substantial property, investments, business interests or large financial payments, transaction-specific tax review can help identify tax consequences before the settlement is implemented.
That. Income-tax law is primarily governed by central legislation. The fact that the matrimonial proceeding is in Pune does not by itself create a separate Pune-specific income-tax regime for alimony or divorce settlements.
This article is provided solely for general legal information and public awareness. It is not legal advice, legal opinion, or a legal solution to any specific facts or circumstances. Laws and their interpretation may change, and the application of law depends upon the facts of each individual matter. Readers should not rely upon this article as a substitute for obtaining appropriate legal advice concerning their specific circumstances. Nothing contained in this article creates, establishes or constitutes an advocate-client relationship between the reader and Trident Legal Services, Advocate Nikhil Rathod, or any other person associated with the publication.
+91 820 890 9423
desk@tridentlegal.in
Flat No. 302, Kalunkhe Niwas, Khopade Nagar, Gujaewadi, Katraj, Pune - 411041


I was really impressed with Trident Legal and Advocate Nikhil Rathod. Even though they just started,
Trident Legal and Advocate Nikhil Rathod are really good at what they do. Even though they
I had a great experience with Trident Legal and Advocate Nikhil Rathod. Even though they are
Trident Legal, with Advocate Nikhil Rathod, is like a rising star in the legal world. I
I was lucky to work with Trident Legal and Advocate Nikhil Rathod. Even though they just
Trident Legal and Advocate Nikhil Rathod are really amazing! They helped me with legal stuff and
Trident Legal and Advocate Nikhil Rathod are like superheroes! They are really good at legal stuff
I wasn’t sure about Trident Legal because they are new, but they surprised me! Advocate Nikhil
I had the honor of working with Trident Legal and Advocate Nikhil Rathod. They were really
Trident Legal, led by Advocate Nikhil Rathod, is like a superhero in the legal world. Even
Mutual divorce and bank accounts, investments and financial assets in Pune: understand joint accounts, fixed…
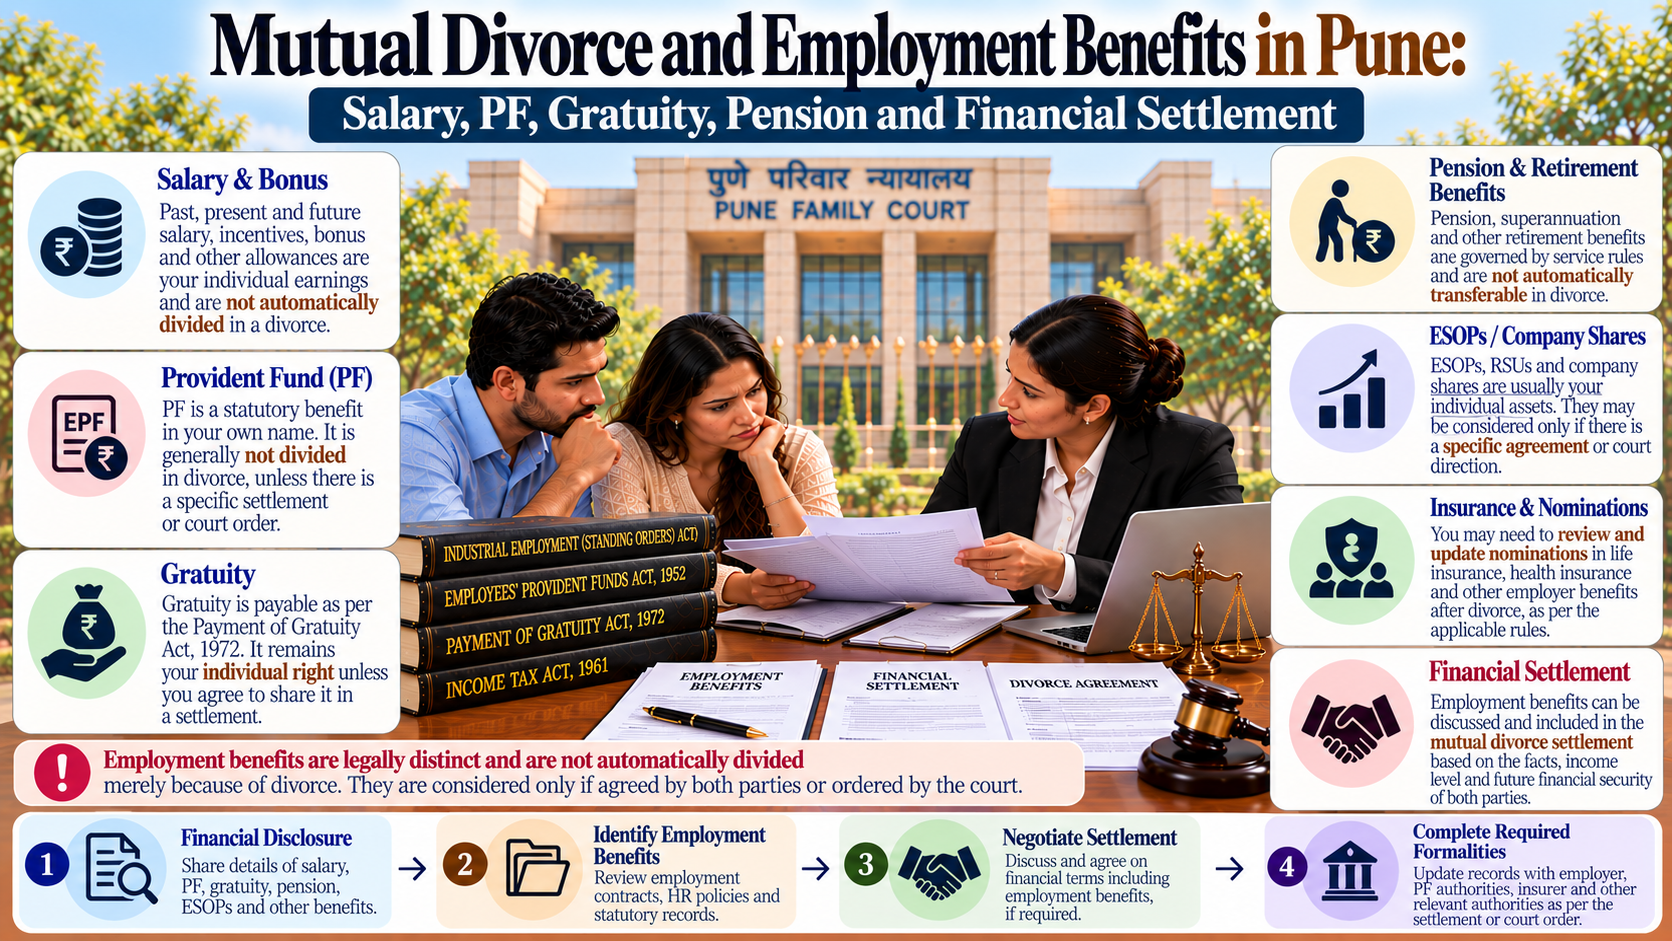
Employment-related benefits can become an important part of financial discussions during a mutual divorce. A…
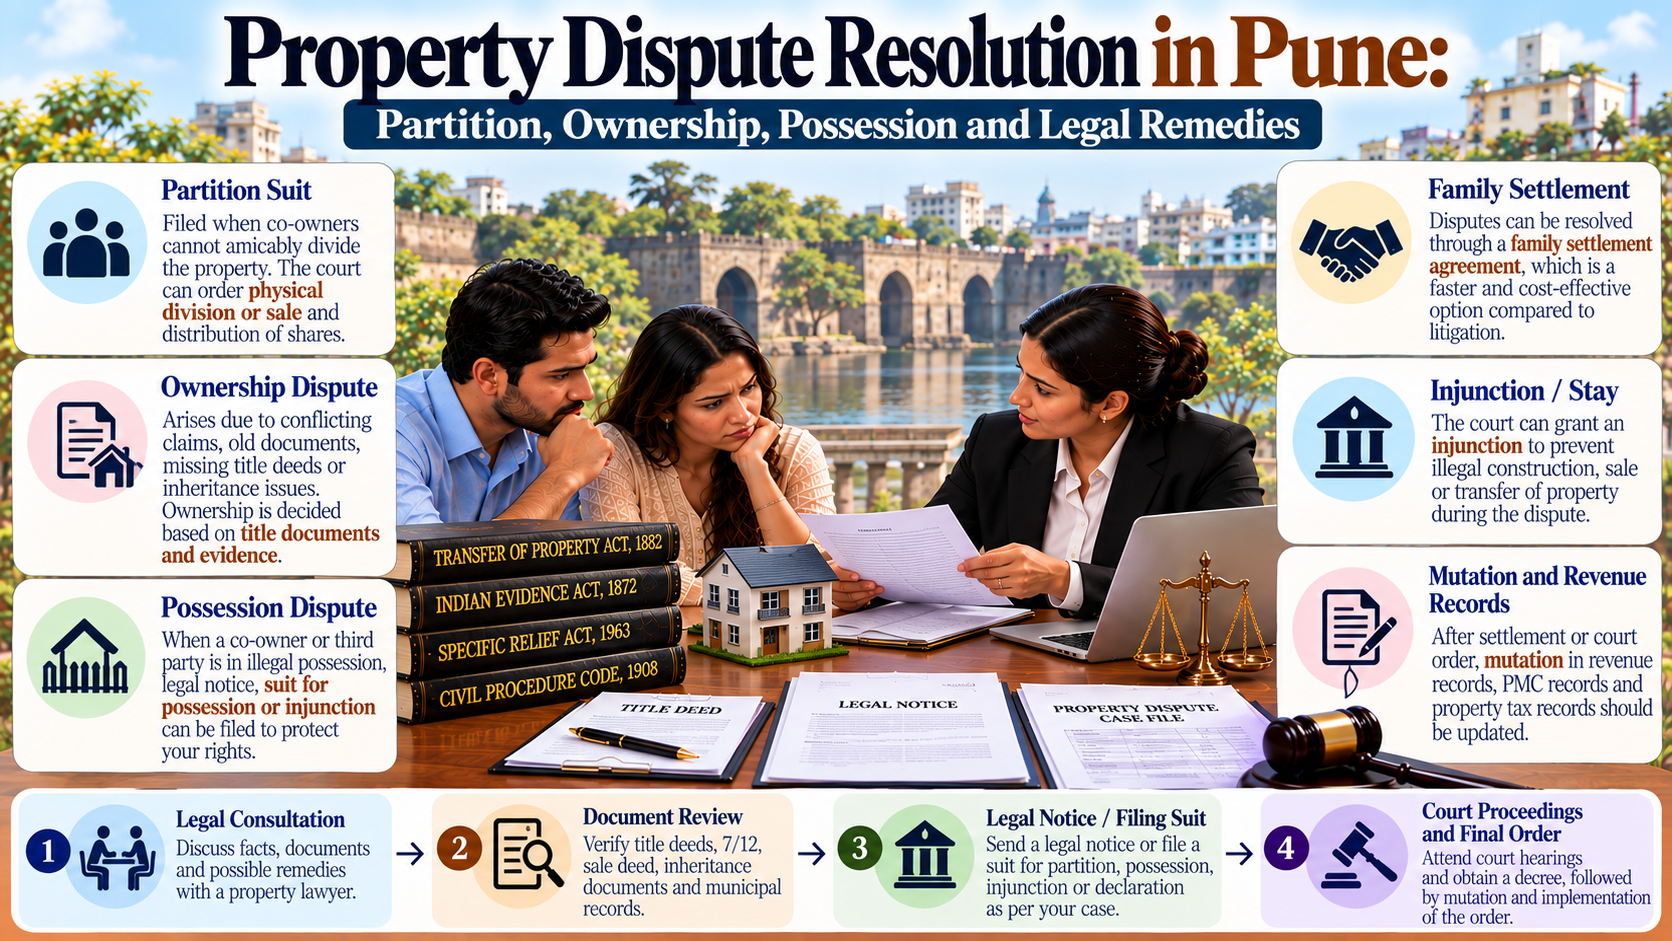
Business ownership can make a mutual divorce settlement more complex because a spouse’s financial position…
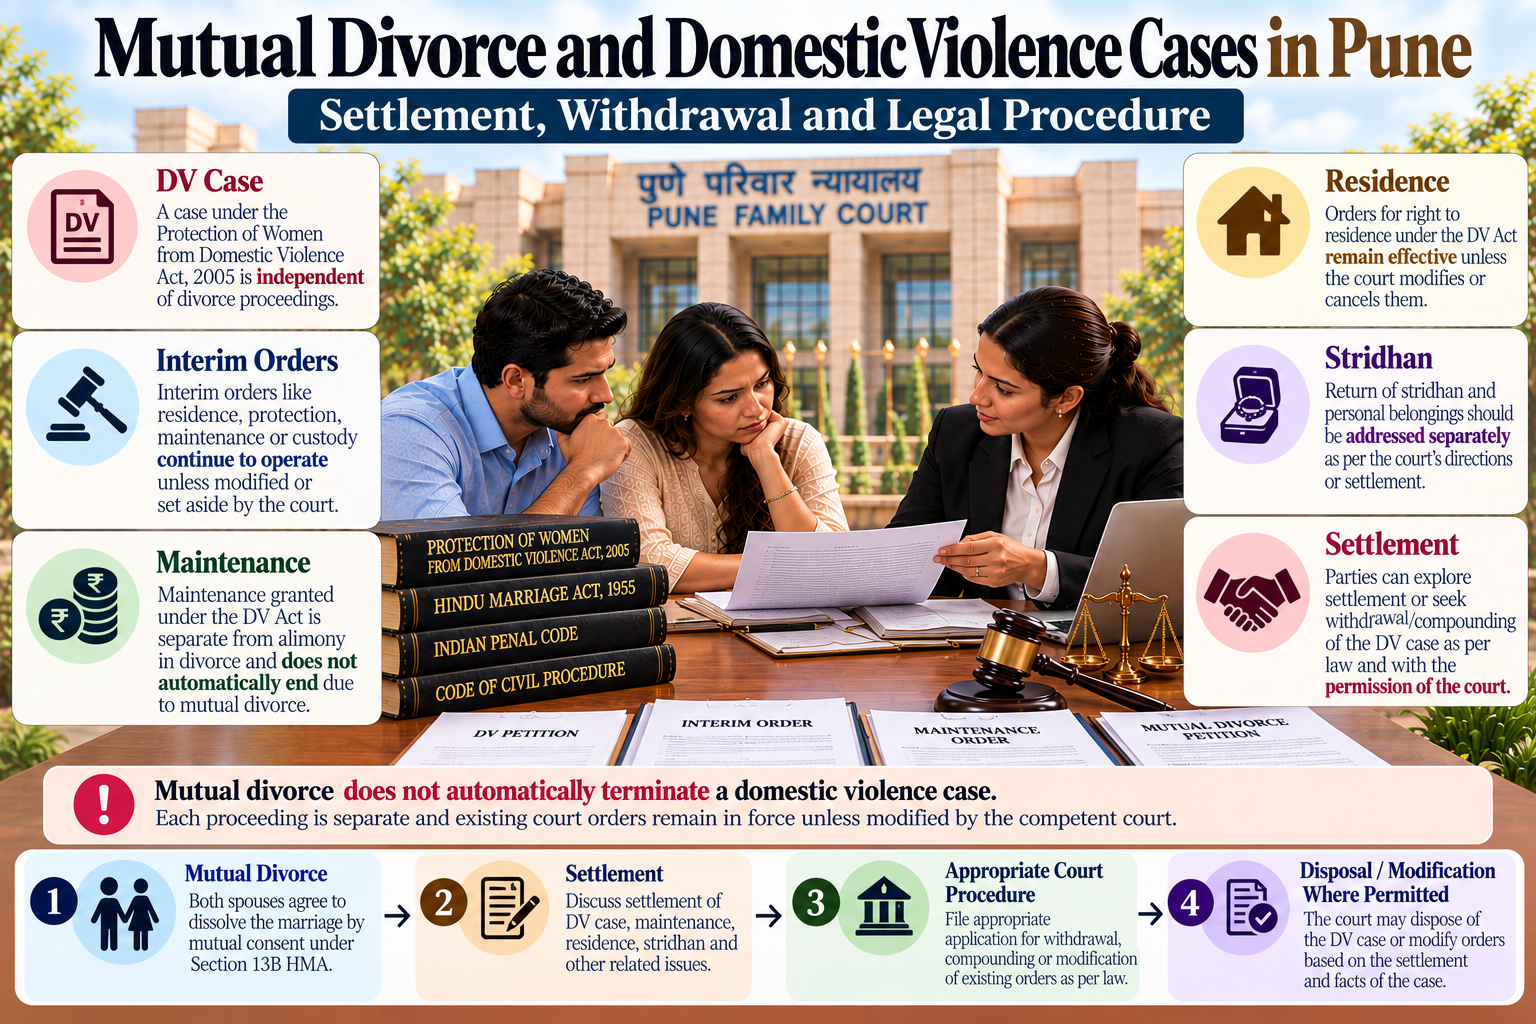
Mutual divorce and proceedings under the Protection of Women from Domestic Violence Act, 2005 may…
That. Mutual divorce and proceedings under the Protection of Women from Domestic Violence Act, 2005…

A home loan can make a mutual divorce settlement substantially more complicated because the marriage…